
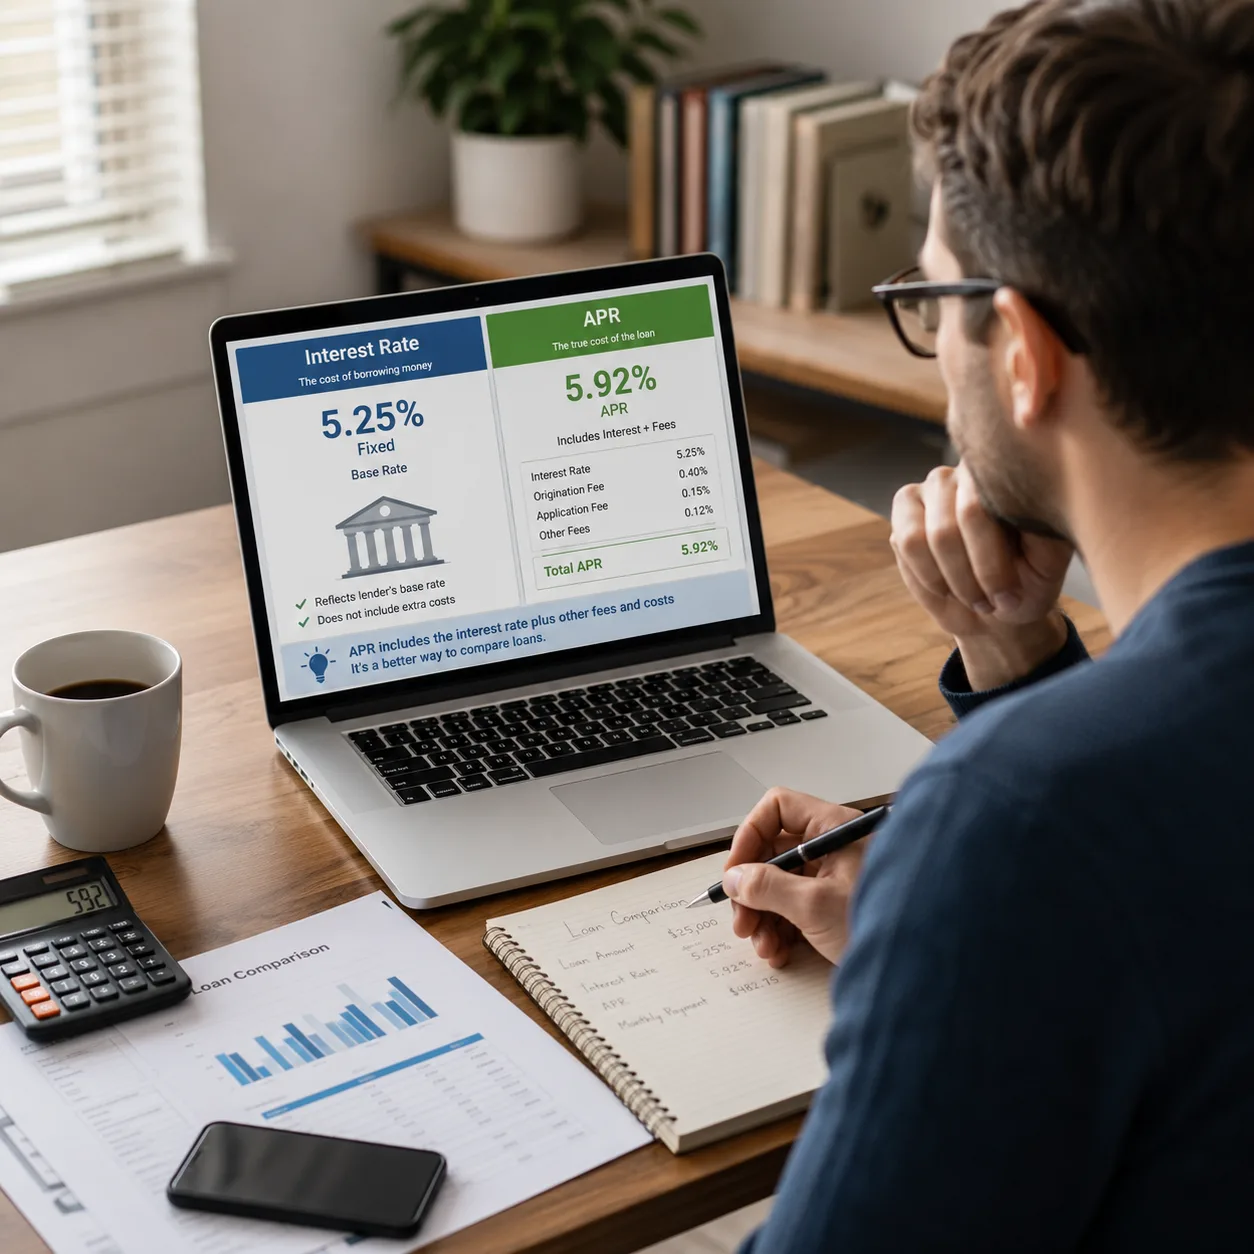
Understanding APR vs interest rate on a loan is the single most useful skill for comparing borrowing offers. The interest rate is the cost of borrowing the principal; the APR adds in fees to show the loan’s true annual cost. Confusing the two can make an expensive loan look cheap. This guide explains both clearly and shows you how to use them together.
Quick answer: The interest rate is the percentage a lender charges on the loan principal. The APR (annual percentage rate) includes that interest plus fees like origination charges, so it reflects the loan’s full yearly cost. When comparing loans, the APR is the more honest number.
Interest rate: the base cost
Your interest rate determines the interest portion of each payment. On a loan, the lender charges it against your outstanding balance. A lower interest rate means lower monthly interest, but the rate alone does not capture fees, which is where APR comes in.
APR: the all-in cost
The APR rolls the interest rate together with mandatory fees, most commonly the origination fee, into one annualized percentage. Because of those fees, the APR is usually higher than the interest rate. The Truth in Lending Act requires U.S. lenders to disclose the APR precisely so borrowers can compare loans on equal footing.
A quick example
| Loan | Interest rate | Origination fee | APR |
|---|---|---|---|
| Loan A | 10.0% | 0% | 10.0% |
| Loan B | 9.0% | 5% | ~11.5% |
Loan B advertises the lower interest rate, but once the 5% origination fee is included, its APR is actually higher. Comparing APRs reveals that Loan A is the cheaper deal, which the headline rate alone would have hidden.
How to use both numbers
- Compare offers by APR. It is the apples-to-apples cost measure.
- Use the interest rate to estimate payments. It drives your monthly interest.
- Watch the fees. A big gap between rate and APR signals high fees.
- Consider the term. APR does not capture how a longer term increases total interest paid.
Frequently asked questions
Because the APR includes both the interest rate and mandatory fees, such as origination charges. The interest rate covers only the cost of borrowing the principal, so the fee-inclusive APR is usually higher.
Use the APR. Because it bundles in fees, it lets you compare the true annual cost of different loans on equal footing, even when their fee structures differ.
Yes. If a loan has no fees, its APR equals its interest rate. That is why a no-fee loan with a slightly higher rate can still be cheaper overall than a low-rate loan loaded with fees.
Educational content, not financial advice.