
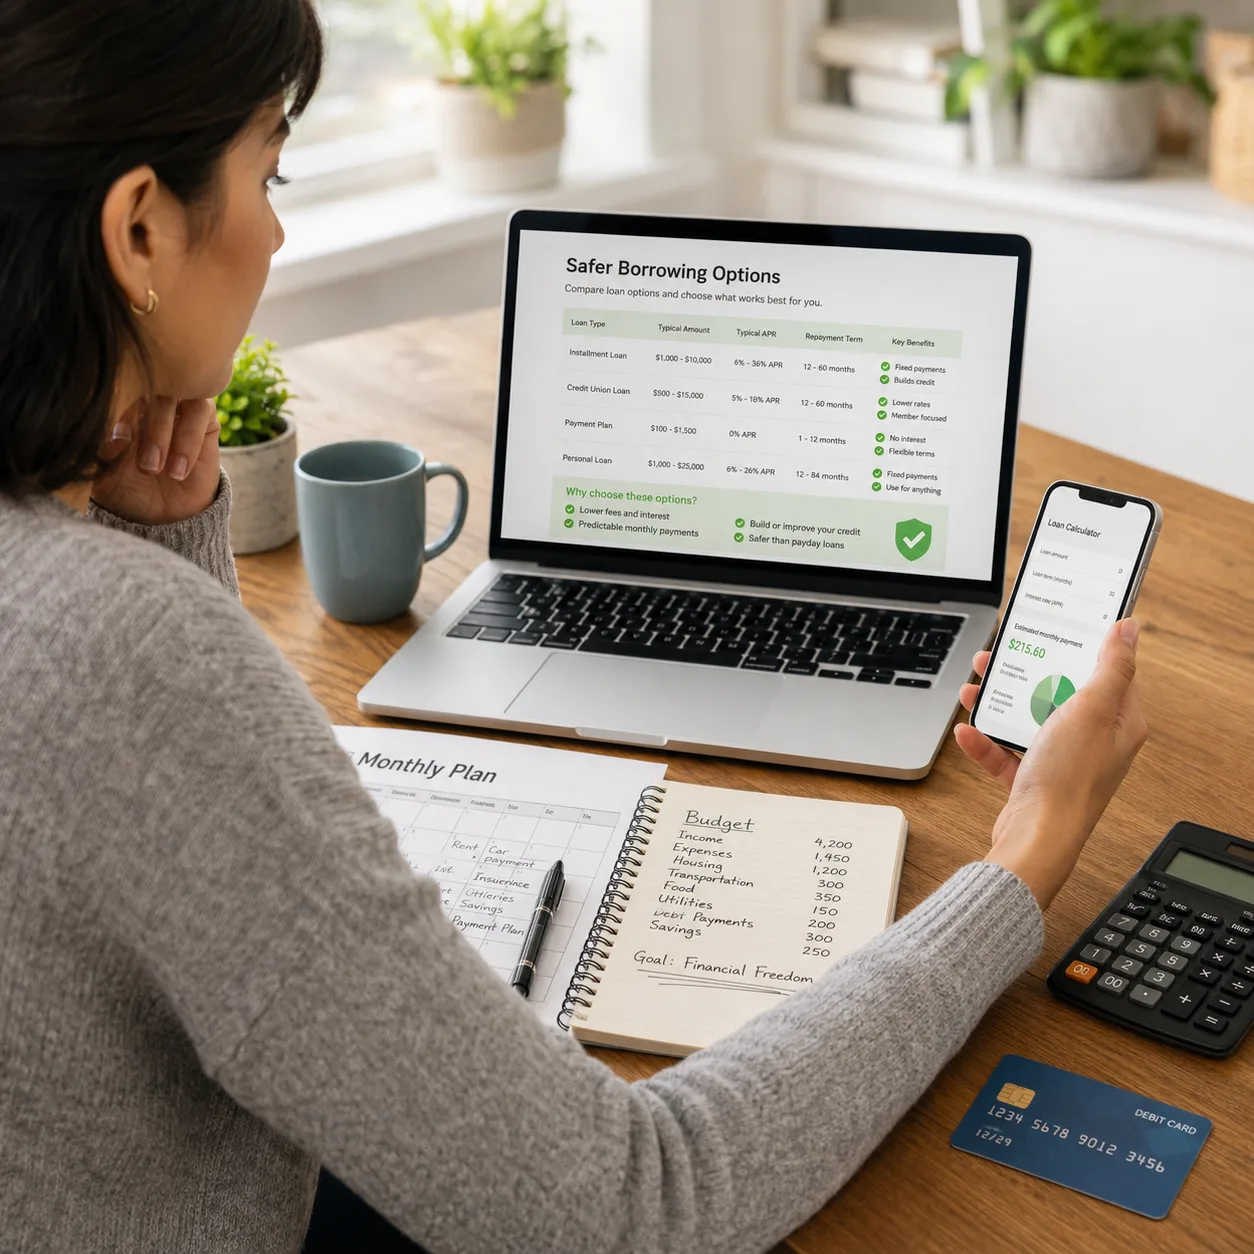
Payday loan alternatives are lower-cost ways to cover a short-term cash gap without the triple-digit APRs and rollover traps of payday lending. With the average payday APR near 391%, almost any alternative saves you money. This guide walks through seven safer options, roughly in order of cost, so you can find the cheapest one you qualify for.
Quick answer: The safest payday loan alternatives include credit-union Payday Alternative Loans (interest capped at 28%), small personal installment loans, paycheck advance apps, a 0% credit-card grace period, borrowing from family, employer advances, and local assistance programs. Each costs far less than a payday loan’s ~391% APR.
Seven safer options
- Payday Alternative Loans (PALs). Offered by federal credit unions. The interest rate is capped at 28%, and the only charge permitted beside it is an application fee limited to the credit union’s actual processing cost and never more than $20 — so the disclosed APR on a small, short loan can come out a little above 28%. Amounts are small by design: $200 to $1,000 over one to six months, or up to $2,000 over twelve months under PAL II.
- Small personal installment loans. Online and credit-union loans with APRs typically in the 8%–36% range, repaid over months.
- Paycheck advance apps. Earned-wage access tools that advance part of your pay, often for a small fee or tip.
- Credit-card cash flow. Using an existing card within its grace period, or a 0% intro offer, beats payday APRs even with card interest.
- Family or friends. An interest-free loan, with clear written terms to protect the relationship.
- Employer advance. Many employers will advance earned wages with no fee.
- Local assistance. Community programs, nonprofits, and utility hardship plans can cover essentials directly.
How the costs compare
| Option | Typical cost | Best for |
|---|---|---|
| Payday loan | ~391% APR | Almost never the best choice |
| PAL (credit union) | Up to 28% interest | Small emergencies, members |
| Personal installment loan | 8%–36% APR | Larger amounts over time |
| Paycheck advance app | Small fee or tip | Bridging to next payday |
| Employer advance | Often free | Quick, no-interest gap fill |
Before you borrow at all
Sometimes the cheapest option is not a loan. Ask creditors for a short payment extension, tap an emergency fund, sell unused items, or contact a nonprofit credit counselor. If you do borrow, choose the lowest-APR option you qualify for and confirm you can repay on schedule.
Frequently asked questions
Usually an employer advance or an interest-free loan from family, followed by a credit-union Payday Alternative Loan capped at 28% interest. All cost a tiny fraction of a payday loan’s average ~391% APR.
Yes. PALs, paycheck advance apps, and many small installment loans are designed for borrowers with limited or poor credit, and they remain far cheaper than payday loans.
Reputable earned-wage access apps are generally safe and inexpensive, but watch for high optional “tips” or fast-funding fees that can add up. Read the terms and treat repeated use as a sign to address the underlying cash-flow gap.
Educational content, not financial advice. If you are facing ongoing cash shortfalls, a nonprofit credit counselor can help.